Key Takeaways for Homeowners
- 15-Year Rule Enforced: Major NJ property insurers now flag architectural shingles over 15 years old and 3-tab shingles over 10–12 years old for non-renewal.
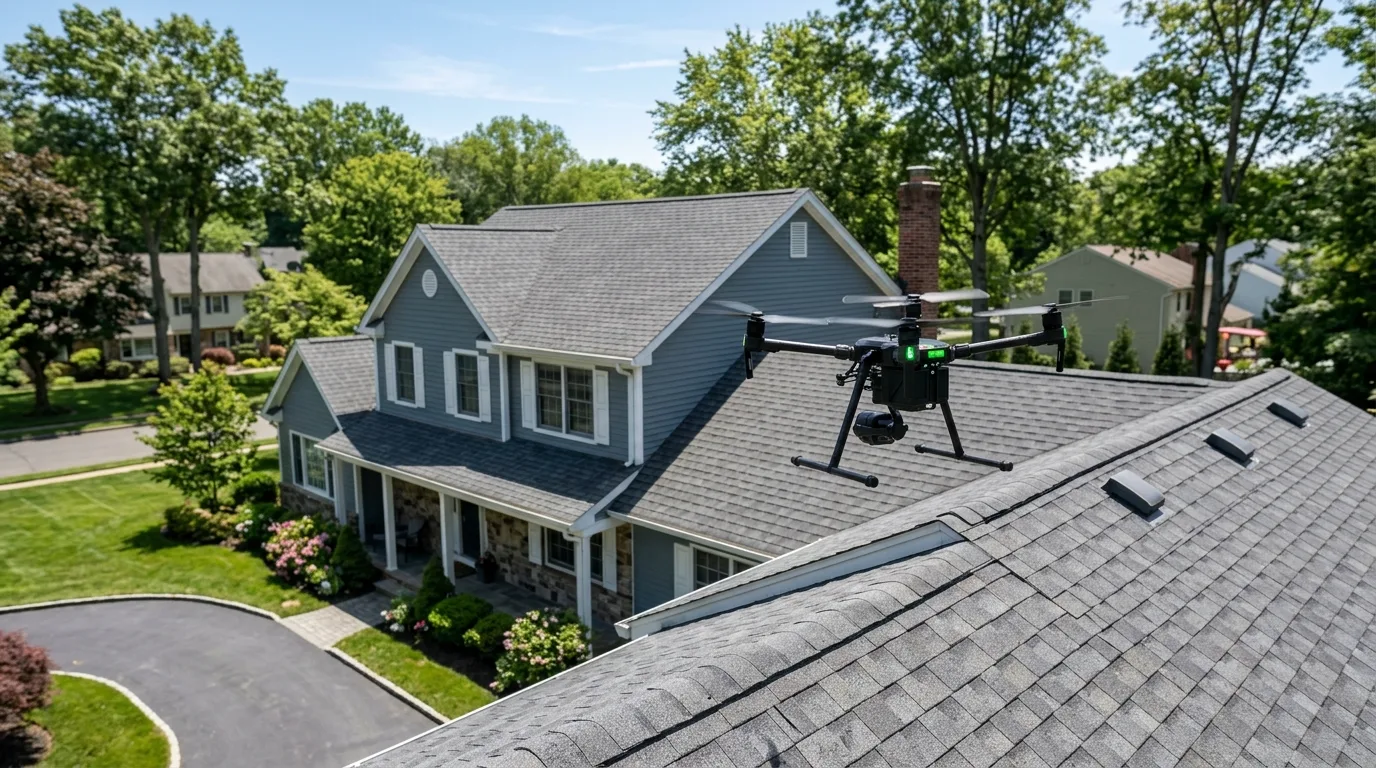
- High-Res Aerial Surveillance: Insurers contract third-party drone and satellite companies that detect moss, curling edges, and rusted valley flashing remotely.
- Official Roof Condition Certifications: A licensed New Jersey roofing contractor can inspect the roof and issue a formal 3-to-5-year life expectancy certificate to satisfy underwriters.
- Targeted Repairs May Suffice: If the roof is structurally sound, professionally soft-washing algae and replacing damaged pipe boot flashings can reverse cancellation notices.
- Mortgage Escrow Risk: Allowing your policy to lapse triggers high-cost forced-place insurance from your mortgage servicer, making swift action critical.
Why New Jersey Insurers Are Dropping Policies Over Roof Age
Over the past two years, homeowners throughout Bridgewater, Somerville, Basking Ridge, and Warren have opened their mail to find unexpected cancellation, non-renewal, or conditional coverage notices from top-tier carriers like Travelers, State Farm, Allstate, Chubb, and New Jersey Manufacturers (NJM).
Following consecutive years of severe coastal nor'easters, destructive hail swarms, winter ice dam backups, and localized microbursts, property and casualty actuaries have completely restructured underwriting models. What was historically considered a long-term structural component with a 25-to-30-year operational horizon is now scrutinized after just 12 to 15 years. If your architectural shingles have reached their teenage years, insurance risk models assume an impending leak, structural rot, or catastrophic blow-off is an actuarial certainty.
Rather than waiting for winter snow loads or torrential rain to trigger an interior drywall collapse or five-figure water damage claim, carriers issue an uncompromising ultimatum: provide a certified contractor inspection proving at least 3 to 5 years of verified remaining functional life, execute contracted repairs or a complete roof replacement in Bridgewater, NJ within 30 to 60 days, or face immediate policy termination.
Carrier Underwriting Comparison: New Jersey Policy Rules
Different insurance carriers operating in Somerset County impose varying restrictions once an asphalt shingle roof crosses the 10-to-15-year threshold:
| Carrier Type | Strict Age Threshold | Surveillance Method | Common Underwriting Action Taken |
|---|---|---|---|
| National Direct Writers (State Farm, Allstate, Liberty Mutual) |
15 to 20 Years | Annual drone sweeps and geospatial satellite scans | Mandatory replacement notice or policy non-renewal within 30 days unless certified by an NJ HIC contractor. |
| Regional NJ Carriers (NJM, Plymouth Rock, Selective) |
15+ Years | Third-party drive-by photo audits and physical loss inspections | Requirement to treat cosmetic moss, replace damaged pipe boots, or install a new architectural shingle system. |
| High-Value Specialty (Chubb, Pure, Cincinnati) |
20 Years | Comprehensive on-site loss prevention engineering surveys | Mandates preemptive tear-off to maintain full replacement cost coverage on luxury estates. |
The Danger of ACV Depreciation Endorsements
Even if your insurance company does not outright cancel your homeowner policy, underwriters frequently execute a quiet but devastating policy amendment: converting your roof coverage from Replacement Cost Value (RCV) to Actual Cash Value (ACV).
Under standard Replacement Cost Value, if a severe storm tears off your 15-year-old roof, the insurance carrier pays the full modern cost to replace it with brand-new materials (minus your hurricane or wind deductible). For a typical $16,000 project, your out-of-pocket expense is limited to your deductible.
Under an Actual Cash Value roof endorsement, the insurer applies steep annual depreciation schedules—often deducting 5% to 7% of the roof's value for every year since installation. On a 16-year-old roof, an insurer may calculate 75% depreciation. If that storm occurs, the carrier will only issue a check for $4,000, leaving you personally responsible for the remaining $12,000 balance!
At Bridgewater Roofer, our team works closely with homeowners to prevent these punitive endorsements. We perform detailed physical roof condition inspections to document structural stability, preserve your full RCV policy status, or provide itemized quotes for complete replacements using our Somerset County roofing cost calculator.
How Aerial and Drone Scans Flag Your Property
Many homeowners ask: "How did my insurance company even know my roof has moss if nobody knocked on my door or walked on my property?"
New Jersey insurance carriers now employ high-resolution aerial imagery platforms (such as Nearmap and EagleView) paired with autonomous drone inspection networks. Algorithms scan satellite sweeps and flyovers, analyzing pixel color density and texture variations for:
-
Black Algae Streaks & Moss Clusters: Indicates retained moisture and organic decay on shaded North-facing slopes. See our specialized guide on removing roof moss and Gloeocapsa magma black streaks safely.
-
Cupping, Curling, and Shingle Lift: Thermal stress causing shingle tabs to separate from the underlying adhesive strip, increasing vulnerability to high wind shears.
-
Granule Loss in Valleys: Shiny fiberglass mats reflecting sunlight through thin asphalt layers, indicating advanced UV breakdown.
-
Temporary Tarping Remnants: Any blue or black emergency tarp visible from the sky triggers an automatic non-renewal flag. Review our protocol for emergency roof repairs and leak containment.
Somerset County Microclimates: Why Local Roofs Age Faster
Roof longevity in Central New Jersey varies dramatically based on regional geography, elevation, and tree canopy density. Underwriters pay special attention to homes in distinct Somerset County communities:
| Community Area | Dominant Environmental Stressors | Typical Shingle Lifespan Impact |
|---|---|---|
| Martinsville & Warren | High elevation along the Watchung Mountains, violent wind turbulence, severe winter ice sheets. | Shingle thermal sealant strips weaken 3–5 years earlier due to continuous wind buffeting. |
| Basking Ridge & Bedminster | Dense mature oak canopy, heavy shade, acid leaf mulch retention, and rampant moss growth. | Shaded northern roof slopes suffer accelerated moisture rot and fungal decay under heavy tree cover. |
| Bound Brook & Manville | Raritan River basin humidity, valley temperature inversions, intense summer thunderstorms. | Elevated humidity accelerates algae staining and thermal blistering on low-pitch roofs. |
| Somerville & Raritan | Historic residential architecture, multi-gabled Victorian steep pitches, older chimney mortar joints. | Chimney counter-flashing degradation and pipe boot cracking are primary causes of flagged insurance reports. |
| Hillsborough & Branchburg | Expansive suburban layouts, open wind corridors across former farmland, severe driving rain. | Exposed southwest roof slopes experience high UV degradation and thermal shock from summer heatwaves. |
The Official Roof Condition Certification Process
If your insurance carrier flagged your roof erroneously, you have the right to contest their automated drone assessment with an official Roof Condition Certification conducted by a licensed New Jersey Home Improvement Contractor (NJ HIC #13VH09876500).
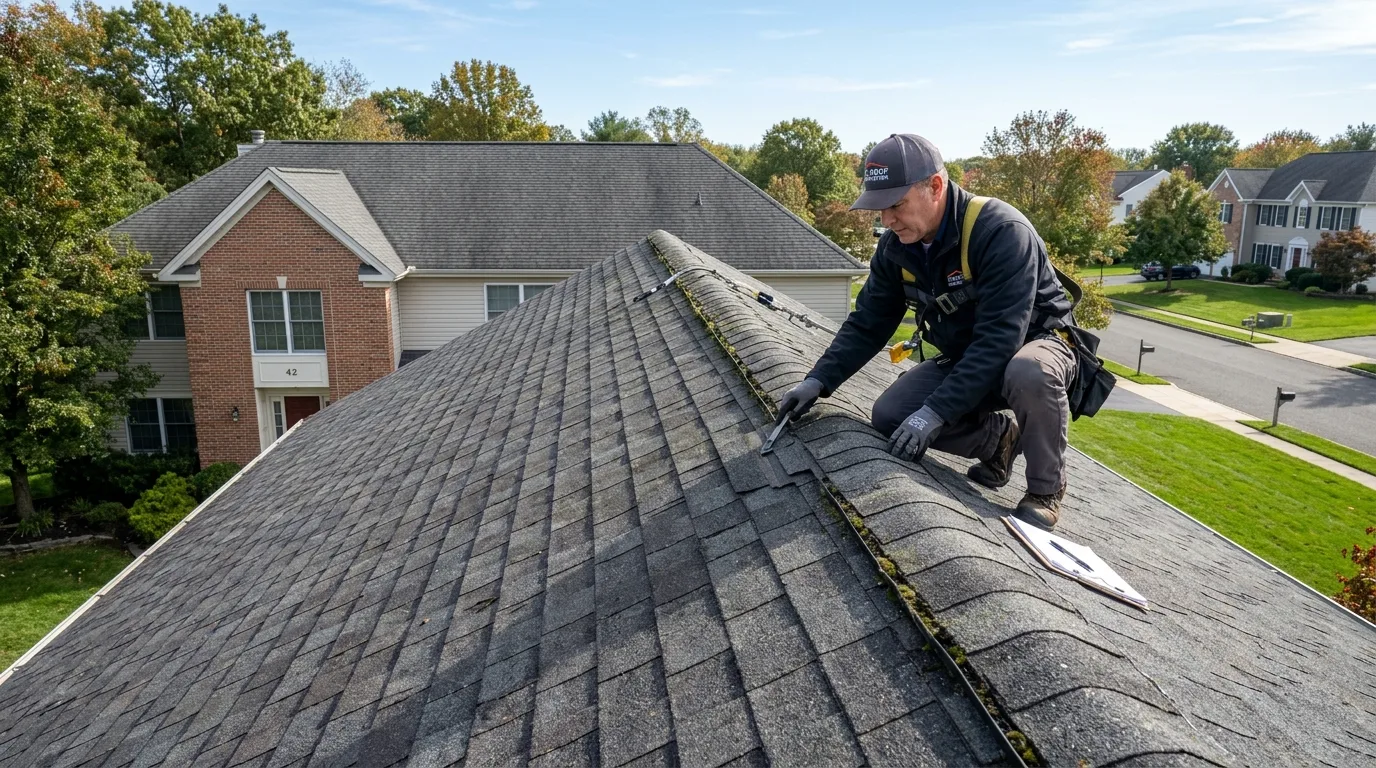
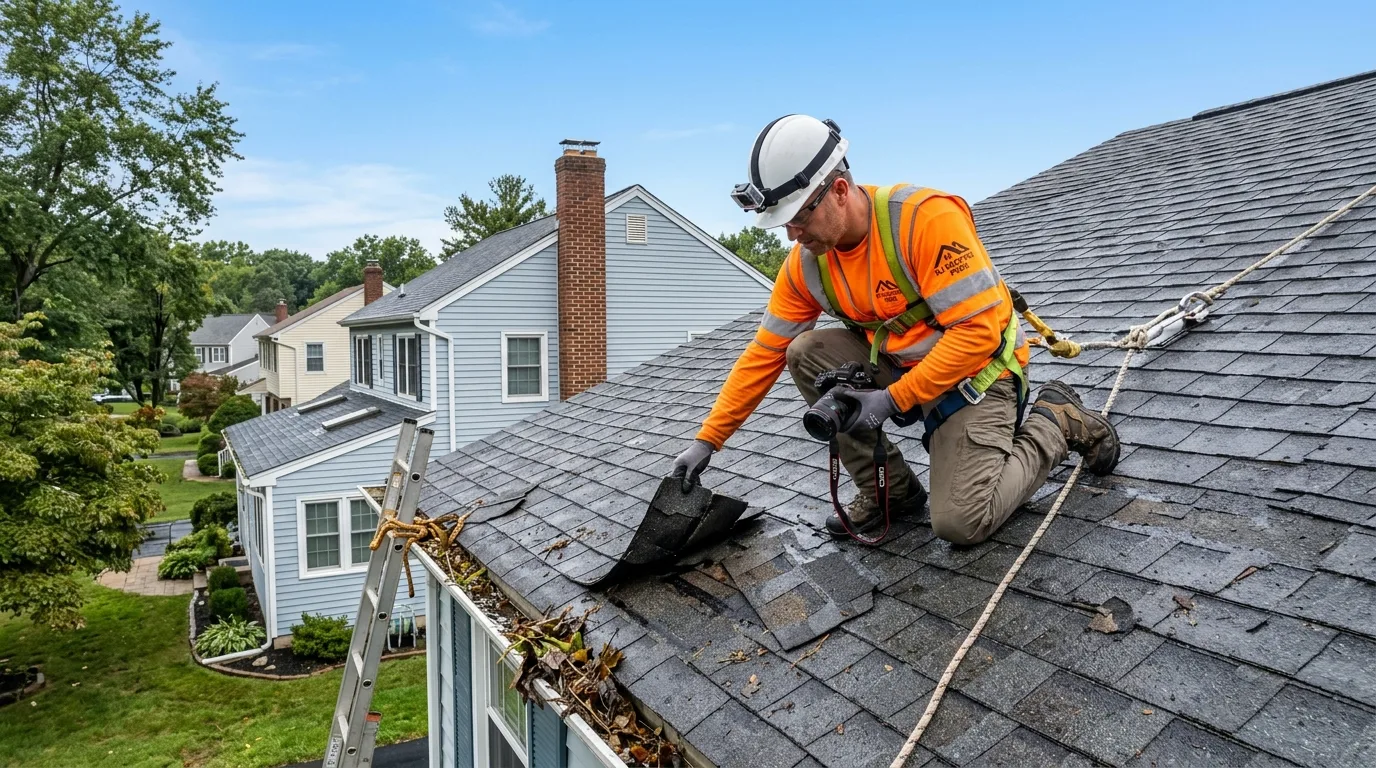
At Bridgewater Roofer, our certified inspectors perform an exhaustive 21-point physical assessment:
- Granule Retention Testing: Measuring remaining ceramic granule depth across high-wear slopes to ensure adequate UV shielding.
- Seal Strip Flexibility: Verifying that asphalt thermal bonds remain intact and resist 110+ MPH wind uplifts.
- Flashing Integrity: Inspecting chimney step flashing, plumbing boot neoprene, and valley metalwork. See our detailed guide to chimney flashing leak repairs in NJ.
- Attic Decking Inspection: Checking the underside of plywood for moisture staining, delamination, or mold caused by attic condensation.
- Gutter & Drainage Evaluation: Ensuring seamless gutters and downspouts channel water safely away from fascia boards.
- Signed Engineering Report: Formulating an official, photographic letter for your insurance underwriter stating the verified remaining functional lifespan (typically 3 to 7 years).
Satisfying the Underwriter: Targeted Repair vs. Replacement
In many cases, full replacement is not immediately mandatory. If the underwriter flagged your home for cosmetic moss or 4–5 wind-damaged shingles, performing targeted professional roof repair coupled with safe low-pressure soft washing can satisfy the underwriting team.
However, if the shingles are genuinely brittle across all slopes, granule loss exposes fiberglass mats, or the roof has exceeded 20 years, scheduling a complete roof replacement is the only permanent solution. Our team prepares municipal permits through the local building department (see our Bridgewater roofing permit guide) and provides the signed contract paperwork to your insurance agent immediately so your policy remains active.
If your roof was impacted by recent severe weather, you may also qualify for insurance-funded storm restoration. Review our comprehensive diagnostic checklist on what to check on your roof after a NJ storm to identify hidden wind creases and hail strikes before your claim window expires.
Timelines & Mortgage Compliance Warnings
If your homeowners insurance policy lapses, your mortgage lender will be notified automatically via electronic escrow hookups. Under the terms of your deed of trust, lenders will purchase force-placed insurance on your behalf. Force-placed insurance is typically 200% to 300% more expensive than standard policies, protects only the lender's loan balance (not your personal belongings or liability), and is billed directly to your monthly mortgage escrow.
Taking fast action with a licensed local contractor ensures you remain in complete control of your home insurance coverage and budget.
Need an Expert Assessment on Your Roof?
Talk directly with an experienced Somerset County field tech. 100% Free on-site inspection.
Frequently Asked Questions
Yes, New Jersey insurance companies can legally non-renew policies based on roof age or exterior condition even if no active leaks exist. Underwriters evaluate the statistical risk of future failure, flagging roofs over 15–20 years old, heavy moss growth, or missing shingles detected via aerial drone imagery.
A Roof Certification Letter is an official document signed by a licensed NJ roofing contractor stating that an existing roof has been inspected and possesses 3 to 5+ years of remaining functional life. Most insurance underwriters accept this formal engineering report to overturn an impending cancellation notice.
We provide rapid 24-to-48-hour emergency inspection scheduling for homeowners facing imminent insurance deadlines across Somerset County. Our inspectors examine all slopes, document condition with date-stamped photography, and deliver your completed certification report within 24 hours of inspection.
Homeowners insurance only covers roof replacements resulting from sudden, accidental storm, hail, or fallen limb damage—not gradual aging. If our forensic inspection uncovers unfiled wind or hail damage from recent Somerset County storms, we provide forensic documentation to file a legitimate storm claim.